Neoclassical Theories of Organization
The classical organization theories concentrated on discipline and the economic well-being of people. They ignored their morale and desires.  Neoclassical organization theories while accepting the merits of classical theories have given more importance to human relations and behavioral sciences. The neoclassical theories of organization modified, added and extended the classical theories by realizing the fact that management exists in a social system wherein human factors have cognizant roles to perform. Employees can play crucial roles in the decision-making process. Approaches of  Neoclassical Theories of Organization Human Relations and Behavioral Science have become two important approaches of neoclassical theories. 1. Human Relations Theory The human relations theory was developed by Elton Mayo and his associates from 1924 to 1932 at the Hawthrone plant of Western Electric Company.   They experimented in four phases: Illumination experiment, relay assembly test, interviewing programs and the bank wiring observations room experiments. Illumination experiments revealed that Continue reading
International Human Resource Selection Procedures

Multinational Corporations (MNCs)  use a number of selection procedures. The two most common are tests and interviews. Some international firms use one; a smaller percentage employ both. Theoretical models containing the variables that are important for adjusting to an oversea assignment have been developed. These adjustment models can help contribute to more effective selection of expatriates. The following sections examine traditional testing and interviewing procedures, then present an adjustment model. Testing and Interviewing Procedures Some evidence suggests that although some firms use testing, it is not extremely popular. For example, an early study found that almost 80 percent of the 127 foreign operations managers who were surveyed reported that their companies used no tests in the selection process. This contrasts with the more widespread testing that these firms use when selecting domestic managers. Many  Multinational Corporations report that the costs, questionable accuracy, and poor predictive record make testing of limited Continue reading

Accounting Errors – Meaning, Causes and Types

The errors or mistakes which are committed in the journal, ledger and any other financial statements are known as accounting errors. Accounting errors may be defined as those mistakes which are generally committed while recording the financial transactions in the book of accounts. These errors may be committed while recording the transactions in the journal and posting them in the ledger accounts. Such errors may be technically committed or committed due to lack of the knowledge of accounting principles and rules. Generally, accounting errors are unintentional. However, it may intentionally be committed so as to take some undue advantage. Accounting errors distort the true business results. Therefore, these errors must be properly located and rectified for ascertaining the true profit or loss and financial position of the business. Major Causes of Accounting Errors There can be several causes of accounting errors. The following are the important ones: Lack of Knowledge: Continue reading

Market-Based and Resource-Based Theories of Competitive Advantage

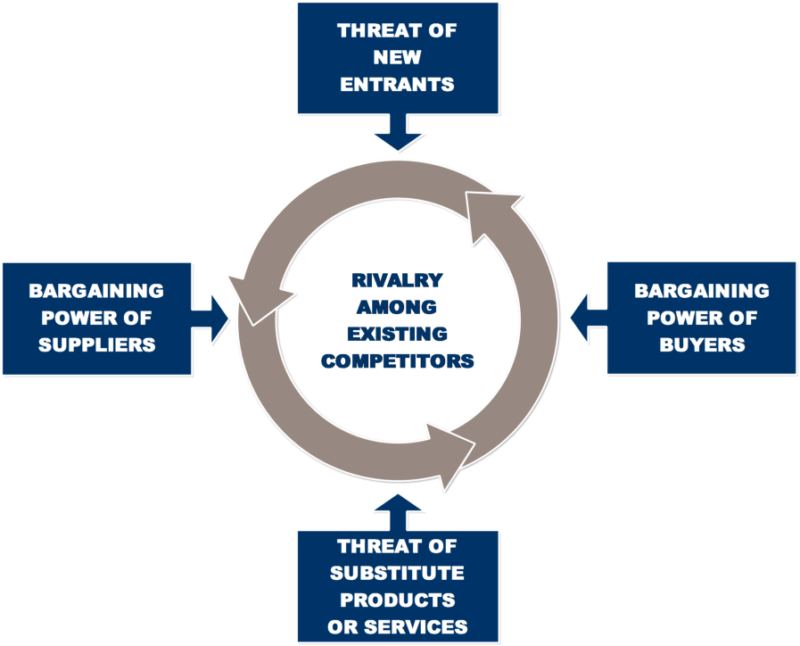
The competitive advantage, a concept introduced by Michael Porter in 1985 has become one of the key concepts in management science today. A firm is said to have a competitive advantage when it is implementing a value creating strategy not simultaneously being implemented by any current or potential competitors. Over the past 25 years, a large body of literature engaged in analyzing how organisations can achieve and, more importantly, sustain a competitive advantage. During this process, two different perspectives or ‘schools of thought’ emerged. The first school of thought is that an organization’s competitive ability depends more on the external environment and industry attractiveness. This perspective is referred to as the market based view and was largely triggered by Porter.  The second school of thought is based on the internal environment i.e. the fundamental attributes of an organisation, in terms of strengths and weaknesses determine a firm’s ability to compete. Continue reading

Role and Significance of Budgetary Control

Budgetary control has the existence of broad and narrow sense. Broad budgetary control sees the entire budget system as a control system, which it is the formation of a prior, during and after the whole process control system. Through the budget preparation, budget evaluation, reward and punishment by monitoring of budget execution. Narrow budgetary control prepares a good budget as a basis for performance management and standards on a regular basis to compare actual performance with the budget analyze differences in the results and take corrective measures, which is mainly referring to something in the process of budget implementation in the monitoring of behavior. According to control activities, budget control includes target control, process control and system control, while the budget as the primary means of corporate internal controls provides a comprehensive management platform. Budget target of control is that Budget management through strategic planning to determine the annual business Continue reading

Earnings Management – Meaning, Definition, Motives and Strategies

Over the past two decades there has been collapses in corporate sector affecting various companies including Enron, American International Group (AIG), HIH Insurance and National Bank of Fiji. Due to these collapses, the need for proper management of the earning or revenue generated by the company has become the very significant part as main objective of every company. Along with this objective, managers of the organization have different incentives to manage the earning of the company. Management of earnings means structuring the financial transactions and statements in the manner so as to have maximum benefit. It tries to mislead the users of the financial statements by presenting the earnings as budgeted or thought by the management instead of presenting the actual performance made by the company during the period. The different incentives for earnings management are – increased managerial remuneration, management buyout and managing the regulatory concerns imposed by different authorities. Continue reading