What is Financial Restructuring?

Financial restructuring is the process of reshuffling or reorganizing the financial structure, which primarily comprises of equity capital and debt capital. Financial restructuring can be done because of either compulsion or as part of the financial strategy of the company. This financial restructuring can be either from the assets side or the liabilities side of the balance sheet. If one is changed, accordingly the other will be adjusted. The two components of financial restructuring are; Debt Restructuring Equity Restructuring 1. Debt Restructuring Debt restructuring is the process of reorganizing the whole debt capital of the company. It involves reshuffling of the balance sheet items as it contains the debt obligations of the company. Debt restructuring is more commonly used as a financial tool than compared to equity restructuring. This is because a company’s financial manager needs to always look at the options to minimize the cost of capital and improving Continue reading

Investments when entire Stock Market is Under or Over Valued

Should management proceed with investing in a project with a satisfactory NPV (Net Present Value) if it has sufficient funds to do so, and if (a) the entire stock market is significantly undervalued and may well rise by 25 or 30% over the next year, or (b) the entire stock market is significantly overvalued and may well fall by 25 or 30% over the next year? In case (a), it could be argued that management should postpone the investment for a year, and invest the cash in a general portfolio of shares, realize them after a year, then take up the postponed investment, and use the capital gain either for future investment or a special dividend payment to shareholders. However, most shareholders do not expect or want the company to use their money for speculative share investments since most companies are unlikely to possess the appropriate skills to do so. Continue reading

Involvement and Participation in Organizational Change

Involvement and participation are perhaps the most powerful techniques management can use to gain acceptance of change. Commitment to carry out these decisions is intensified. Personal satisfaction derived from the job is increased. The extent of personal involvement can range from merely being informed, to discussing problems and voicing opinions and feelings to actually making and implementing decision. At the most superficial level, some participation occurs when one is designated to receive information either written via distribution lists or in face-to-face briefings. At a slightly more intensive level, participation can be gained through individual or group consultations. This process is no more than an extension of the face-to-face discussion. In the process of soliciting inputs, the managers carry this approach to step further. Those present are asked to make suggestions about how the change might be accomplished. Alternately a problem might be assigned to a group for analysis and recommended Continue reading

Role of Different Parties Involved in Industrial Relations

Role of Government in Industrial Relations In recent years the Government has played an important role in regulating industrial relations but the extent of its involvement in the process is determined by the level of social and economic development while the mode of intervention gets patterned in conformity with the political system obtaining in the country and the social and cultural traditions of its people. The degree of Government  intervention is also determined by the stage of economic development. For example, in a developing economy like ours, work-stoppages to settle claims have more serious consequences than in a developed economy and similarly, a free market economy may leave the parties free to settle their relations through strikes and lockouts but in other systems varying degrees of Government  participation is required for building up sound industrial relations. In India, the role played by the Government  is an important feature in the Continue reading

Accounting Treatments for Non-Performing Leases

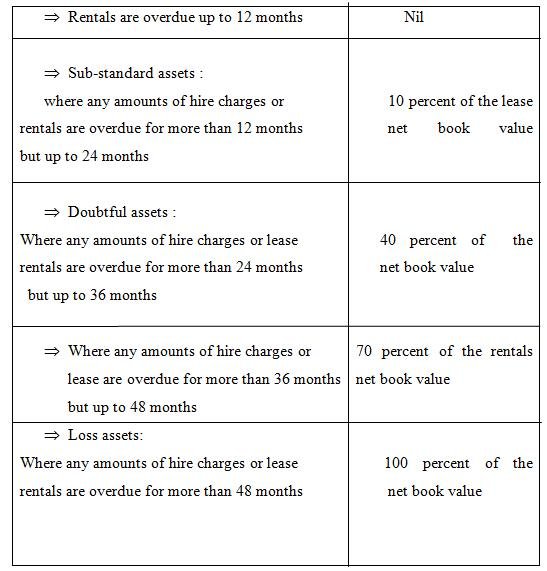
There is no information in the guidance note on lease accounting, 1995, for non-performing assets. The general accounting principles for non-performing assets is contained in accounting standard 9 on Revenue Recognition which is more or less on the lines of the International Accounting Standards on the issue. The Standard provides that whereas, in general, incomes are to be recognized on the basis of accrual, in case of an uncertainty in the ultimate realization of an income, the treatment is as follows: If the uncertainty is prevalent at the time of raising the claim for the income, the recognition of the income shall be postponed If the uncertainty arises subsequent to the claim being made, there shall be a provision made to the extent of the uncertainty. This statement lays down the basic difference between a provision against an income, and non-recognition of income, which is very significant. The accounting for Continue reading

Prospect Theory in Behavioral Finance

The Prospect Theory was originally conceived by Kahneman and Tversky (1979) and later resulted in Daniel Kahneman being awarded the Nobel Prize for Economics. The work by the authors is considered as path breaking in behavioral finance. They introduced the concept of prospect theory for the analysis of decision making under risk. This theory is considered to be seminal in the literature of behavioral finance. It was developed as an alternative model for expected utility theory. It throws light on how individual evaluate gain or losses. The prospect theory has three key aspects. People sometimes exhibit risk aversion and sometimes risk loving behaviors depending on the nature of the prospect. This is due to the fact that people give lower weight age to the outcomes which are probable as compared to those that are certain. This makes them risk averse for choices with sure gains while risk seekers for choices Continue reading