Concept of Goal Congruence

Goal congruence is the term which describes the situation when the goals of different interest groups coincide. A way of helping to achieve goal congruence between shareholders and managers is by the introduction of carefully designed remuneration packages for managers which would motivate managers to take decisions which were consistent with the objectives of the shareholders. Agency theory sees employees of businesses, including managers, as individuals, each with his or her own objectives. Within a department of a business, there are departmental objectives. If achieving these various objectives also leads to the achievement of the objectives of the organization as a whole, there is said to be goal congruence. Achieving Goal Congruence Goal congruence can be achieved, and at the same time, the ‘agency problem’ can be dealt with, providing managers with incentives which are related to profits or share price, or other factors such as: Pay or bonuses related Continue reading
The Edgeworth Box

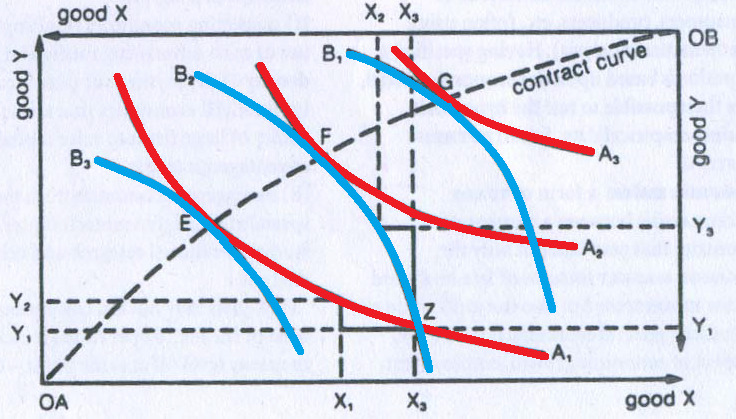
In 1881,  Francis Y. Edgeworth  came up with  a way of representing, using  the same axis,  indifference curves  and  the corresponding  contract curve  in his book “Mathematical Psychics: an Essay on the Application of Mathematics to the Moral Sciences”.  It was  Vilfredo Pareto, in his book “Manual of Political Economy”, 1906, who developed Edgeworth’s ideas into a more understandable and simpler diagram, which today we call the Edgeworth box. Edgeworth box a conceptual device for analyzing possible trading relationships  between two  individuals or countries, using indifference curves. It is constructed by taking the indifference map of one individual (B) for two goods (X and Y) and inverting it to face the indifference map of second individual (A) for the same two goods. Thus,  Edgeworth box is a traditional visualization of the benefits potentially available from international trade. Individual A’s preferences are depicted the three indifference curves A1, A2 and corresponding Continue reading

Developing the Internal Capability for Change Management

One of the fundamental challenges facing leaders today is how to regularly transform the business through major change initiatives, with minimum disruption. Change is changing: it is becoming more frequent, radical and complex. Research suggests that 70% of projects fail to secure their anticipated benefits because organizations install new systems, processes or practices, but fail to implement the change fully–people are not sufficiently personally committed to the new ways of working to sustain them. Developing the internal capability for Change Management is an essential step in assuring the successful implementation of any change project. It is also a factor that will enable the organization to continue to optimize its performance in response to changing service demands and new strategic drivers. To develop the internal process management capability organizations should: Define the roles in Change Management, and where possible, involve the future change managers in the analysis and re-design Establish and Continue reading

Residential Status and Tax Liability in India – Income Tax Basics

The scope of total income is determined on the basis of residential status of the assessee. For the purposes of Income Tax Act, there can be three residential status. Residential status is determined on the basis Basic conditions and Additional conditions Resident and ordinarily resident Resident but not ordinarily resident Non resident. RESIDENTIAL STATUS OF AN INDIVIDUAL Resident and Ordinarily Resident [ROR] An individual is said to be resident in India if he satisfies anyone of the basic conditions and both of the additional conditions. Resident but Not Ordinarily Resident [RNR] An individual is said to be resident but not ordinarily resident in India if he satisfies anyone of the basic conditions but does not satisfies both of the additional conditions. Non Resident [NR] If an individual does not satisfies any of the basic conditions he is said to be non resident in India Basic conditions Additional conditions A stay Continue reading

Industrial Development Bank of India (IDBI)

Industrial Development Bank of India was set up to accelerate the development of the country. A number of financial institutions came into existence after independence and were catering to a variety of needs of the industry. There was a lack of co-ordinating different institutions and it led to overlapping and duplication in their efforts. At the same time some gigantic projects of national importance were not getting required financial assistance. It was in response to this need that the Industrial Development Bank of India (IDBI) was established in 1964 as a wholly owned subsidiary of Reserve Bank of India. The bank was to act as an apex institution co-coordinating functions of all the financial institutions into a single integrated movement of development banking and supplementing their resources for industrial financing and as an agency for providing financial support to all worthwhile projects of national importance whose access to existing institutional Continue reading

Organization Structure – Definition, Determinants, Importance and Types

An organization structure is a set of planned relationships between groups of related functions and between physical factors and personnel required for the performance of the functions. The organization structure is generally shown on the organisation chart. It shows authority and responsibility between various positions in the enterprises by showing who reports to whom. Organization structure lays down the pattern of communication and coordination in the enterprises. Though organization structure is very important, it is not an end in itself. According to Peter F. Drucker, “Organisation is not an end itself, but a means to end of business performances and business results. Organization structure is an indispensable means; and the wrong structure will seriously impair business performance and may even destroy it. Organization structure must be designed so as to make possible the attainment of the objectives of the business for five, ten, fifteen years hence.” Organizing Function of Management Continue reading