Theories of International Investments

International investments mean investments beyond borders. International investments refer to investments by entities of a nation in nations other than their own. Foreign investments involve export of capital. The opportunity for International investments is directly emanating from economic reformist policies adopted by most of the countries of the world including centrally planned and command economies. Liberalization, Privatization and Globalization (LPG) are vigorously pursued by the countries giving an up-thrust on investment opportunities. Broadly there are two types of foreign investment, namely, foreign direct investment (FDI) and foreign portfolio investment (FPI). FDI refers to investment in a foreign country where the investor retains control over the investment. It typically takes the form of starting a subsidiary, acquiring a stake in an existing firm or starting a joint venture in the foreign country. Direct investment and management of the firms concerned normally go together. If the investor has only a sort of Continue reading
Factoring of Receivables – Meaning and Mechanism

Raising short term and medium term debt by inviting and accepting deposits from the investing public has become an established practice with a large number of companies both in the private and public sectors. This is the outcome of the process of dis-intermediation that is taking place in Indian economy. Similarly, issuance of Commercial Paper by high net-worth Corporates enables them to raise short-term funds directly from investors at cheaper rates as compared to bank credit. In practice, however, commercial banks have been the major investors in Commercial Paper in India, implying thereby that bank credit flows to the corporate sector through the route of CPs. Inter-Corporate loans and investments enable the cash rich corporations to lend their surplus resources to those who need them for their working capital purpose. Factoring of receivables is a relatively recent innovation which enables corporates to convert their receivables into liquidity within a short Continue reading

Different Types of Information Systems Used in Different Levels of Management

Information system means by which people and organizations utilize technologies, collect, store use and distribute information. Good information system is used to provide important information for decision making. The information technology may be used for the processing, storing or distribution of data. These technologies collectively include information technology and data. It is an organized combination of people, hardware, software, communications networks, and data resources that stores and retrieves, transform and disseminate information in an organization. Very main functions of information systems is systems analysis and design, that is to say, analyzing a customer’s business condition (or trouble), with deference towards information processing, and designing and implementing an suitable–generally computerized–solution to the difficulty. Information systems professionals who focus in this part are known as systems analysts. The procedure begins with a complete determination of the client’s information needs and business processes. The result normally involves various programming, in addition to the Continue reading

Capital Asset Pricing Model (CAPM) – Definition, Formula and Calculation

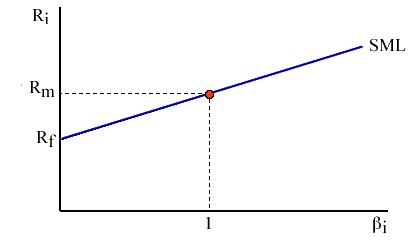
The risk or variation in return of a security is caused by two types of factors. The first type of factors will affect the return of almost all securities in the market. Examples of such sources of risks are changes in the interest rates and inflation of the economy, movement of stock market index and exchange rate movement. The risk caused by such factors is known as systematic risk. Apart from systematic risk, the variation in return of a security is also caused by some other factors which are specific to a security, like a strike in a company or the caliber of the management of a company. The risk caused by such factors is known as unsystematic or specific risk. The unsystematic risk of a security can be diversified away by combining different securities into a portfolio. But systematic risk cannot be diversified away by the construction of a Continue reading

Direct and Indirect Taxes

Taxes are classified as direct tax and indirect tax. But the meaning of these two types of taxes is not clear. For a long time economists interpreted these two types in different ways. For instance, one group of economists considered taxes on production as direct taxes and those on consumption as indirect taxes.  J.S. Mill distinguished these two types of taxes in terms of the ability to shift the tax. Any person on whom the tax is imposed, if he himself pays the tax, it is called direct tax and if he is able to shift the tax to somebody who ultimately pays it then it is called indirect tax. For example, income tax is paid by a person as it is levied on the income earned by him, so it is a direct tax. On the other hand the sales tax imposed on the seller is shifted to the Continue reading

Financing of Current Assets

Current assets of enterprises may be financed either by short-term sources or long-term sources or by combination of both. The main sources constituting long-term financing are shares, debentures, and debts form banks and financial institutions. The long term source of finance provides support for a small part of current assets requirements which is called the working capital margin.  Working capital margin is used here to express the difference  between current assets and current liabilities. Short-term financing of current assets includes sources of short-term credit, which a firm is mostly required to arrange in advance. Short-term bank loans, commercial papers etc. are a few of its components. Current liabilities like accruals and provisions, trade credit, short-term bank finance, short-term deposits and the like warranting the current assets are also referred to a short-term term sources of finance.Spontaneous financing can also finance current assets, which includes creditors, bills payable, and outstanding receipts. Continue reading